
Protect your people. Protect your business.
Group Protection for employers and growing businesses
Start Quote

Having good people matters.
Protecting them well matters more.
You can’t stop what happens to your people.
You can decide what support is there when it does.
Group Life, Group Income Protection and Group Critical Illness Cover can help provide that support.
Start my review
What is Group Protection?
The simplest way to think about Group Protection is insurance provided by an employer for their people.
It can provide a lump sum if an employee dies or becomes critically ill, or a replacement income if illness or injury stops them working.
For your employees, it’s protection paid for by the business. For you, it can strengthen recruitment and retention, but there’s a human benefit too.
If something serious happens to one of your people, you know you’ve put real support in place for them or their family.
Start Quote
The 3 Types
of Group Protection
You can choose to put one benefit in place or build a package using all three.
Looking to add Private Healthcare for your team? - Check out our Private Medical Insurance page here.
*Subject to tax rules at the time


Group Life Insurance
Often known as Death in Service. It can provide a tax-free* lump sum to an employee’s beneficiaries if they die while covered by the scheme.
Group Income Protection
Can provide part of an employee’s income if illness or injury keeps them away from work. Schemes can include return-to-work support.

Group Critical
Illness Cover
Provides a lump sum if an employee is diagnosed with one of the serious illnesses covered by the scheme and meets the insurer’s definition.
Why offer Group Protection?
Good people are hard to find. Even harder to replace.
Group Protection can help you build a benefits package people genuinely value by supporting recruitment, retention and your reputation as an employer.
But there’s another reason. If something serious happens to one of your people, you want to know you did more than just send flowers and a card.
Group Protection can help you:
- Offer benefits people genuinely value
- Strengthen recruitment and retention
- Support employees during longer-term illness
- Provide financial security for employees and their families
- Support employees back to work
- Build a culture where looking after people means more than paying their salary
Start Quote
We’ve got you...
You don’t need to know whether your employees need 3× salary, 4× salary, Income Protection or Critical Illness Cover before you speak to us.
That’s our job.
We’ll understand what you want to do for your people, help you build the right package and compare suitable Group Protection insurers to put it in place.
Good benefits don’t need to be complicated.
Start my review
How much does Group Protection cost?
Probably less than you think. You might spend more on coffee, Christmas parties or software nobody uses.
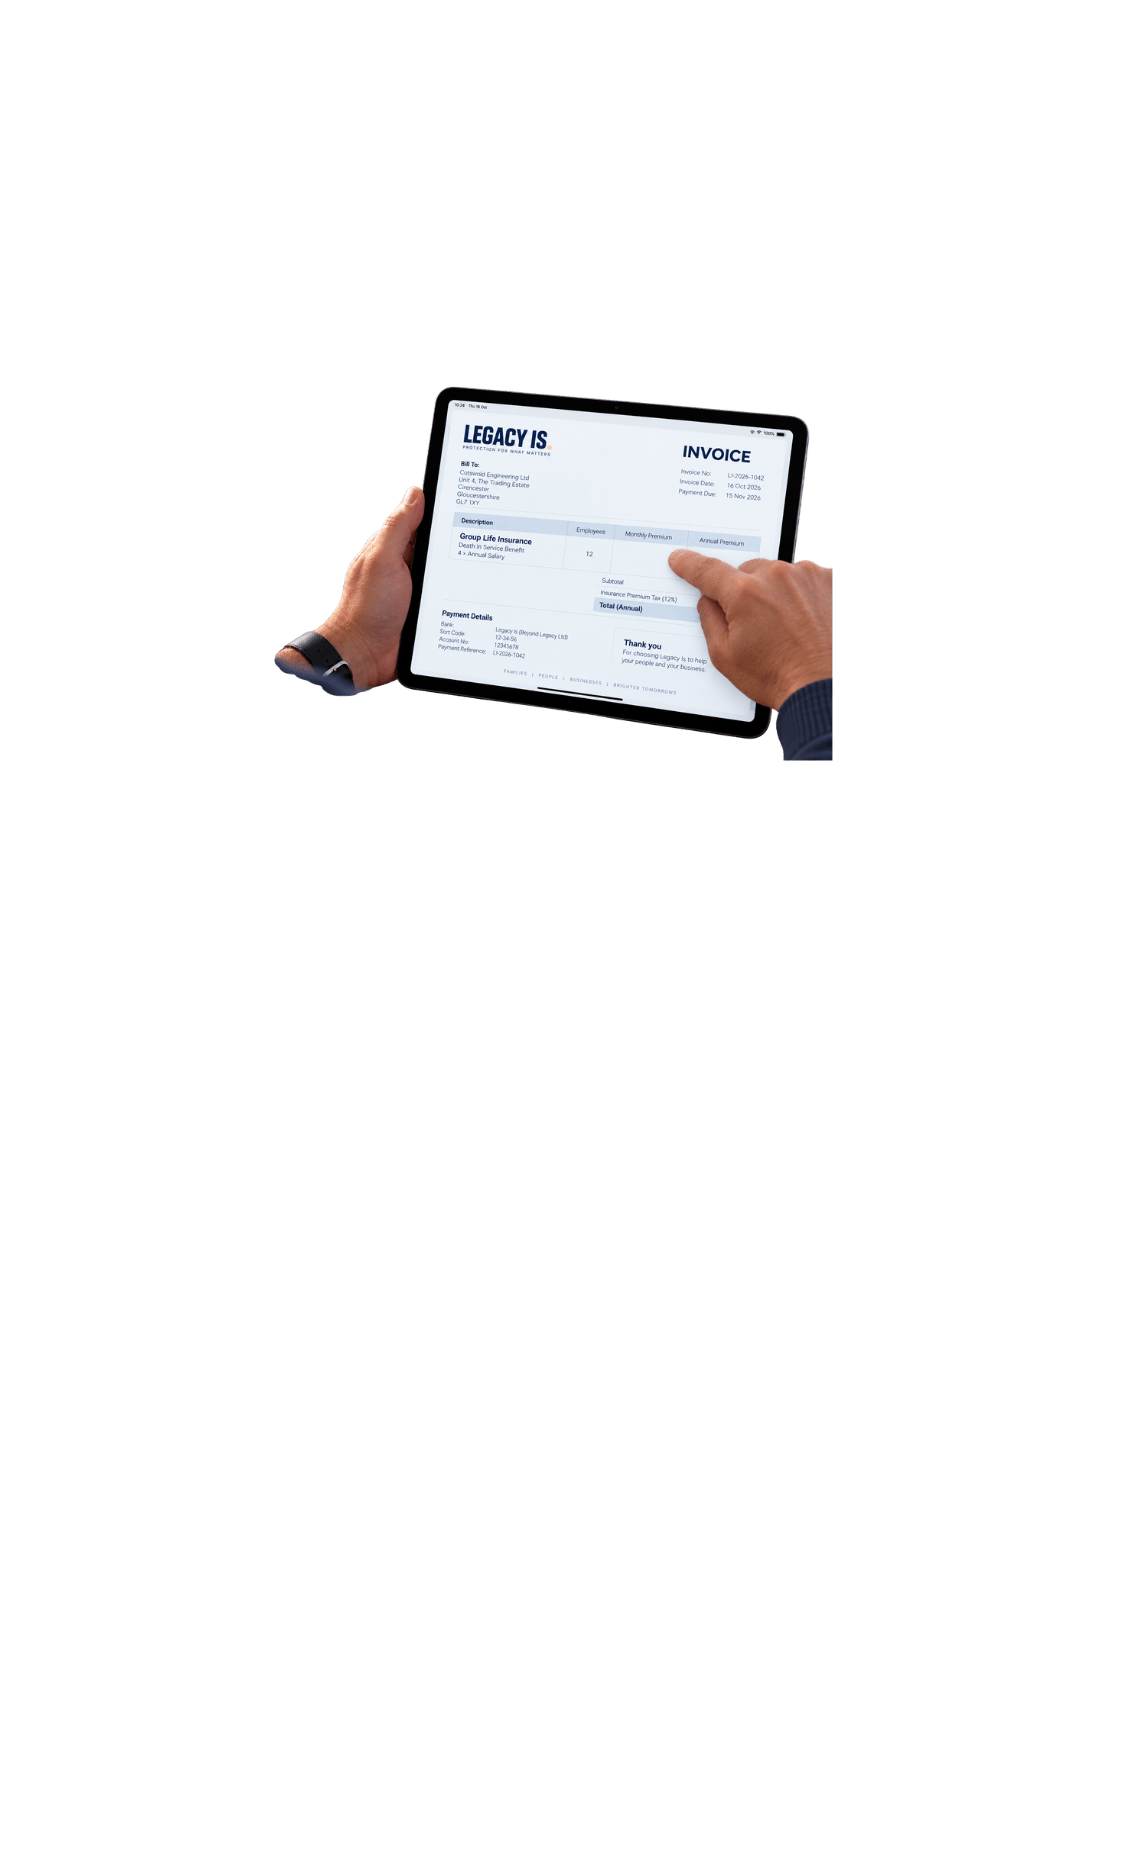
A recent Legacy Is client insured 6 employees for 4× salary Death in Service cover for less than £750 a year.
Group Protection can sometimes be more affordable than you think, and could provide thousands of pounds of support when somebody actually needs it.
So for a small business, good protection doesn’t necessarily mean a huge employee-benefits budget. We can start with what you want to spend and show you what that could provide for your people.
The exact price for you depends on your team and the benefits you choose, but meaningful cover doesn’t always need a huge budget.
Start Quote
£2.69 Billion paid in Group Protection Claims
UK Group Protection insurers paid £2.69 billion in claims in 2025 supporting employees and their families through Group Life, Group Income Protection and Group Critical Illness Cover.*
Source: GRiD 2025 claims data.
For them
If something serious happens, Group Protection can give an employee or their family financial support at the point they may need it most.
For you
Good employee benefits can help you recruit, retain and support the people your business relies on while giving you a clearer structure for what happens when someone becomes seriously ill or can’t work.
With us
“Richard was by far the most approachable broker we found. He took the time to get it right for us and explored all the options. Great service, very professional and highly recommended”
Sports & Entertainment Business - Legacy Is Customer Review
Group Protection for a business like yours.
Small Businesses
2-5 Employees
In a small business, every person matters. If someone is seriously ill, can’t work or dies, the impact can be felt across the whole company. Group Protection can help you look after the people who keep the business running.
Growing Businesses
6-20 Employees
As your team grows, benefits can start to matter more when you’re competing for good people. Group Protection can help strengthen your offer, support retention and show employees there’s more to working for you than salary alone
Established Employer
21+ Employees
Already offer employee benefits? The question becomes whether they’re still doing the job properly. We review existing schemes, benefits & insurers to see whether the cover still gives your people and business good value.
Your next step to getting cover
1. Tell us what mattersWe start with your business and look at how many people you employ, what you already offer and what you want the benefits to achieve. For local businesses, that can mean coming to see you and understanding the business properly.
2. Build the right packageWe work out the level of cover you may need, compare suitable Group Life, Income Protection and Critical Illness options, and help you choose benefits that fit your team and budget. Looking for Private Medical Insurance too? Learn about Business Health Insurance
3. Apply with our helpWe help arrange the scheme, deal with the insurer and make sure you
understand what happens next.
4. Support you and your teamThe job doesn’t stop when the policy starts. We can help explain the benefits to your employees, support changes as your team grows and review the scheme over time to make sure it still works.
You don’t need to know which insurer, benefit level or type of Group Protection you need before speaking to us. That’s what the advice is for.
Start my review
Local Service. Human Advice.
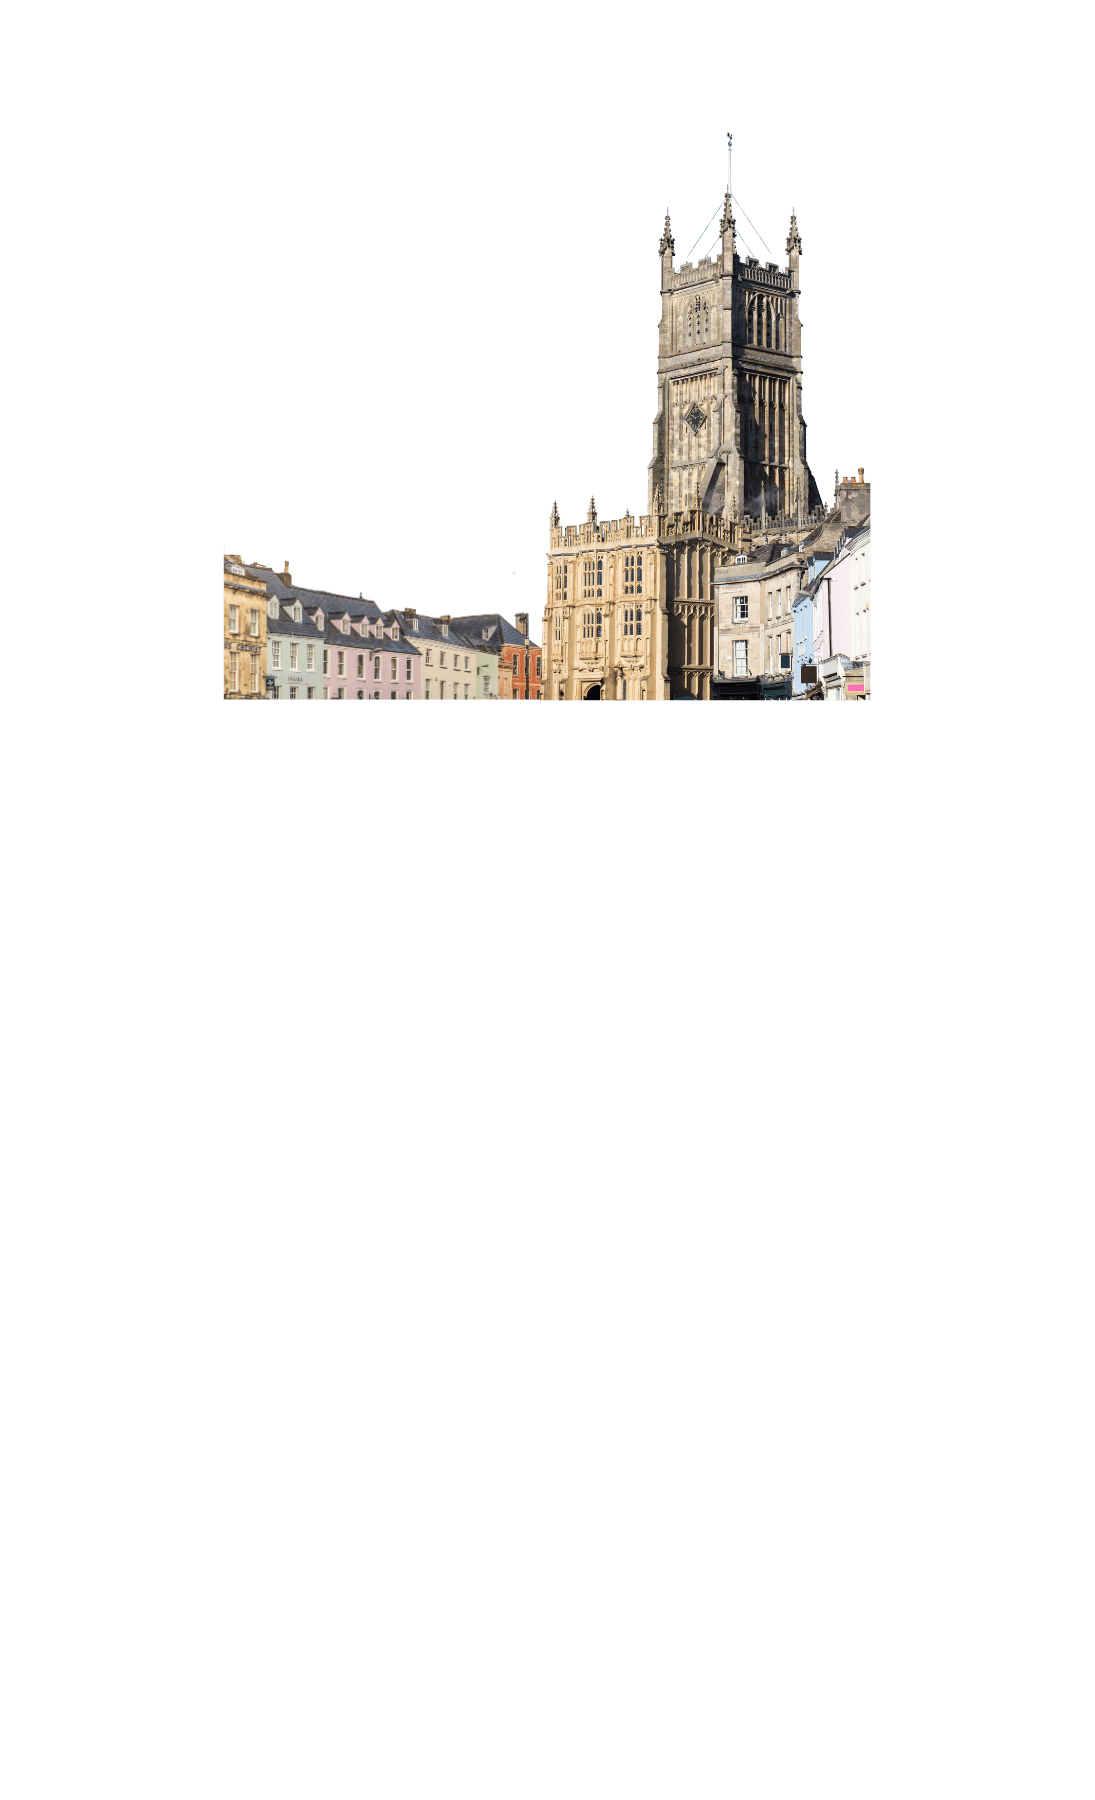
Group Protection advice in Cirencester and the Cotswolds.
Legacy Is works with local employers to put meaningful Life, Income Protection and Critical Illness benefits in place for their people.
Being local means we can do more than send a quote by email. We can come to your business, understand your team, help put the scheme in place and even help explain the benefits to your employees once it starts.
Because if you’re going to spend money protecting your people, they should understand what you’ve given them.
Start my review
Your Group Protection questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Group Protection tax deductible for a business?Often, employer-paid Group Protection premiums can be treated as a business expense, but the tax treatment depends on the benefit and how the scheme is structured. This is one of those areas where getting the structure right matters. We can help you understand the basics and, if needed, liaise with your accountant.
Can company directors be included in Group Protection?Yes, directors can often be included alongside employees. For smaller companies, that can mean protecting the directors and the team through the same arrangement rather than everyone buying separate policies. Different benefit levels can also be set, so directors may have a higher level of cover.
Can I offer different benefits to different groups of employees?Yes, schemes can often be split into clearly defined categories for example directors, managers and other employees all with different benefit levels for each group. The important bit is having a sensible, objective reason for how those groups are defined rather than making it up person by person.
What happens to an employee’s cover if they leave the company?Group Protection normally belongs to the employer, so an employee will usually stop being covered when they leave the business. Some insurers may offer options to continue or replace certain benefits personally, but that depends on the scheme. That’s one of the key differences between workplace protection and cover somebody owns themselves.
How many employees do I need for Group Protection?You don’t need hundreds. Some schemes can start with only 2 employees, although minimum numbers vary by insurer and type of cover. If you’ve got a small team, don’t assume Group Protection isn’t for you.
What is Group Life Insurance or Death in Service?Group Life pays a lump sum if an employee dies in or out of work while they’re covered by the scheme. It’s often expressed as a multiple of salary for example 2× or 4× annual salary. For the employee’s family, that could mean tens or hundreds of thousands of pounds at one of the worst moments of their lives.
What is Group Income Protection?Group Income Protection can pay part of an employee’s salary if illness or injury keeps them off work for a longer period. Many schemes also include rehabilitation, mental health and return-to-work support. It’s not just about paying someone while they’re off, it can help them get back to work too.
What is Group Critical Illness Cover?It can provide an employee with a lump sum if they’re diagnosed with one of the serious illnesses covered by the scheme. That money is theirs to use however they need it, whether that’s paying bills, clearing debt or taking some pressure off while they recover.
Start my review
What we do

About
Protect your people. Protect your business.
Group Protection for employers and growing businesses
Start my Group Insurance review
Having good people matters.
Protecting them well matters more.
You can’t stop what happens to your people.
You can decide what support is there when it does.
Group Life, Group Income Protection and Group Critical Illness Cover can help provide that support.
What is Group Protection?
The simplest way to think about Group Protection is insurance provided by an employer for their people.
It can provide a lump sum if an employee dies or becomes critically ill, or a replacement income if illness or injury stops them working.
For your employees, it’s protection paid for by the business. For you, it can strengthen recruitment and retention, but there’s a human benefit too.
If something serious happens to one of your people, you know you’ve put real support in place for them or their family.
Get Group Protection Quotes
The 3 Types of Group Protection
You can choose to put one benefit in place or build a package using all three.
Looking to add Private Healthcare for your team? - Check out our Private Medical Insurance page here.
*Subject to tax rules at the time
Group Life Insurance
Often known as Death in Service. It can provide a tax-free* lump sum to an employee’s beneficiaries if they die while covered by the scheme.
Group Income Protection
Can provide part of an employee’s income if illness or injury keeps them away from work. Schemes can include return-to-work support.
Group Critical Illness Cover
Provides a lump sum if an employee is diagnosed with one of the serious illnesses covered by the scheme and meets the insurer’s definition.
Why offer Group Protection?
Good people are hard to find. Even harder to replace.
Group Protection can help you build a benefits package people genuinely value by supporting recruitment, retention and your reputation as an employer.
But there’s another reason. If something serious happens to one of your people, you want to know you did more than just send flowers and a card.
Group Protection can help you:
- Offer benefits people genuinely value
- Strengthen recruitment and retention
- Support employees during longer-term illness
- Provide financial security for employees and their families
- Support employees back to work
- Build a culture where looking after people means more than paying their salary
Start my Group Insurance review
We’ve got you...
You don’t need to know whether your employees need 3× salary, 4× salary, Income Protection or Critical Illness Cover before you speak to us.
That’s our job.
We’ll understand what you want to do for your people, help you build the right package and compare suitable Group Protection insurers to put it in place.
Good benefits don’t need to be complicated.
Start my Group Insurance review
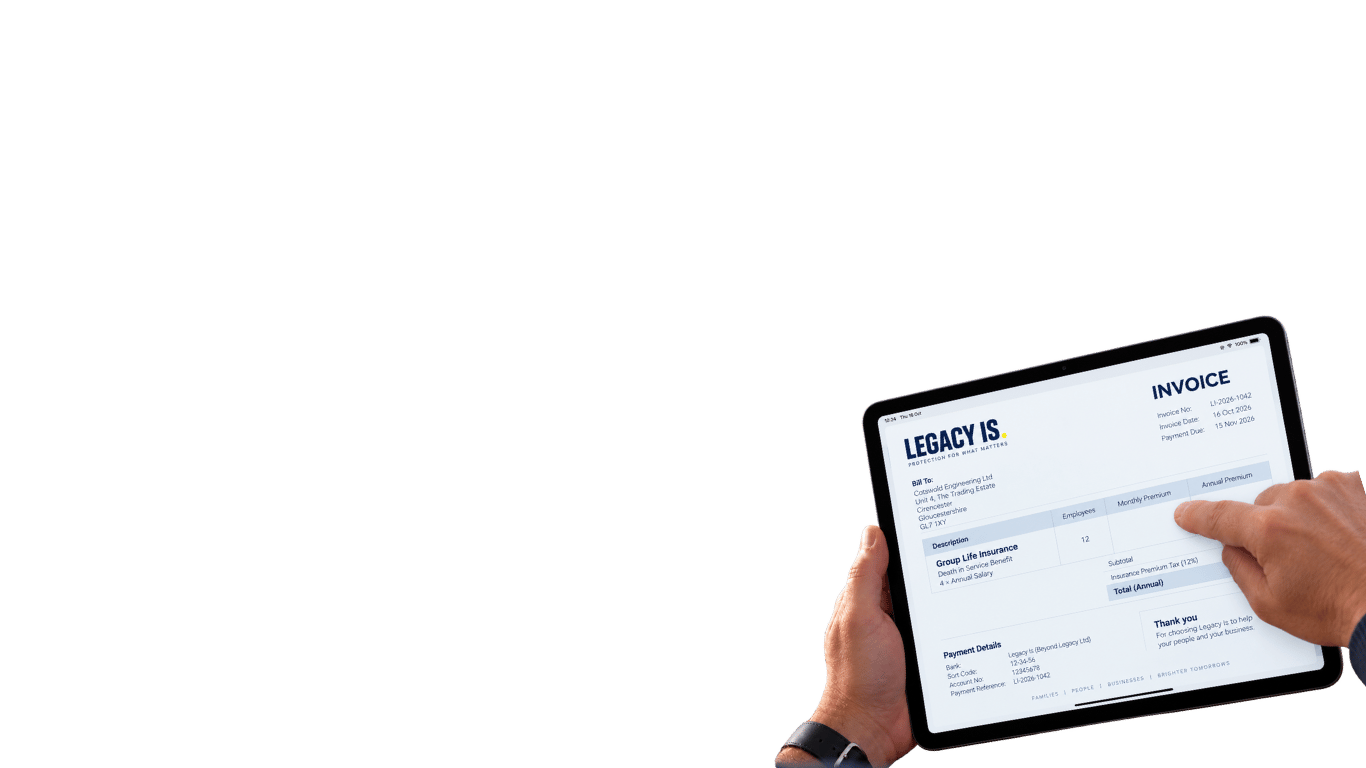
How much does Group Protection cost?
Probably less than you think. You might spend more on coffee, Christmas parties or software nobody uses.
A recent Legacy Is client insured 6 employees for 4× salary Death in Service cover for less than £750 a year.
Group Protection can sometimes be more affordable than you think, and could provide thousands of pounds of support when somebody actually needs it.
So for a small business, meaningful protection doesn’t necessarily mean a huge employee-benefits budget. We can start with what you want to spend and show you what that could provide for your people.
The exact price for you depends on your team and the benefits you choose, but meaningful cover doesn’t always need a huge budget.
Get Group Protection Quotes
£2.69 Billion paid in Group Protection Claims
UK Group Protection insurers paid £2.69 billion in claims in 2025 supporting employees and their families through Group Life, Group Income Protection and Group Critical Illness Cover.*
Source: GRiD 2025 claims data.
For them
If something serious happens, Group Protection can give an employee or their family financial support at the point they may need it most.
For you
Good employee benefits can help you recruit, retain and support the people your business relies on while giving you a clearer structure for what happens when someone becomes seriously ill or can’t work.
With us
“Richard was by far the most approachable broker we found. He took the time to get it right for us and explored all the options. Great service, very professional and highly recommended”
Sports & Entertainment Business - Legacy Is Customer Review
Group Protection for a business like yours.
Small Businesses
2-5 Employees
In a small business, every person matters. If someone is seriously ill, can’t work or dies, the impact can be felt across the whole company. Group Protection can help you look after the people who keep the business running.
Growing Businesses
6-20 Employees
As your team grows, benefits can start to matter more when you’re competing for good people. Group Protection can help strengthen your offer, support retention and show employees there’s more to working for you than salary alone
Established Employer
21+ Employees
Already offer employee benefits? The question becomes whether they’re still doing the job properly. We review existing schemes, benefits & insurers to see whether the cover still gives your people and business good value.
Your next step to getting cover
1. Tell us what mattersWe start with your business and look at how many people you employ, what you already offer and what you want the benefits to achieve. For local businesses, that can mean coming to see you and understanding the business properly.
2. Build the right packageWe work out the level of cover you may need, compare suitable Group Life, Income Protection and Critical Illness options, and help you choose benefits that fit your team and budget. Looking for Private Medical Insurance too? Learn about Business Health Insurance
3. Apply with our helpWe help arrange the scheme, deal with the insurer and make sure you
understand what happens next.
4. Support you and your teamThe job doesn’t stop when the policy starts. We can help explain the benefits to your employees, support changes as your team grows and review the scheme over time to make sure it still works.
You don’t need to know which insurer, benefit level or type of Group Protection you need before speaking to us. That’s what the advice is for.
Start my Group Insurance review
Local Service. Human Advice.
Group Protection advice in Cirencester and the Cotswolds.
Legacy Is works with local employers to put meaningful Life, Income Protection and Critical Illness benefits in place for their people.
Being local means we can do more than send a quote by email. We can come to your business, understand your team, help put the scheme in place and even help explain the benefits to your employees once it starts.
Because if you’re going to spend money protecting your people, they should understand what you’ve given them.
Start my Group Insurance review
Your Group Protection questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Group Protection tax deductible for a business?Often, employer-paid Group Protection premiums can be treated as a business expense, but the tax treatment depends on the benefit and how the scheme is structured. This is one of those areas where getting the structure right matters. We can help you understand the basics and, if needed, liaise with your accountant.
Can company directors be included in Group Protection?Yes, directors can often be included alongside employees. For smaller companies, that can mean protecting the directors and the team through the same arrangement rather than everyone buying separate policies. Different benefit levels can also be set, so directors may have a higher level of cover.
Can I offer different benefits to different groups of employees?Yes, schemes can often be split into clearly defined categories for example directors, managers and other employees all with different benefit levels for each group. The important bit is having a sensible, objective reason for how those groups are defined rather than making it up person by person.
What happens to an employee’s cover if they leave the company?Group Protection normally belongs to the employer, so an employee will usually stop being covered when they leave the business. Some insurers may offer options to continue or replace certain benefits personally, but that depends on the scheme. That’s one of the key differences between workplace protection and cover somebody owns themselves.
How many employees do I need for Group Protection?You don’t need hundreds. Some schemes can start with only 2 employees, although minimum numbers vary by insurer and type of cover. If you’ve got a small team, don’t assume Group Protection isn’t for you.
What is Group Life Insurance or Death in Service?Group Life pays a lump sum if an employee dies in or out of work while they’re covered by the scheme. It’s often expressed as a multiple of salary for example 2× or 4× annual salary. For the employee’s family, that could mean tens or hundreds of thousands of pounds at one of the worst moments of their lives.
What is Group Income Protection?Group Income Protection can pay part of an employee’s salary if illness or injury keeps them off work for a longer period. Many schemes also include rehabilitation, mental health and return-to-work support. It’s not just about paying someone while they’re off, it can help them get back to work too.
What is Group Critical Illness Cover?It can provide an employee with a lump sum if they’re diagnosed with one of the serious illnesses covered by the scheme. That money is theirs to use however they need it, whether that’s paying bills, clearing debt or taking some pressure off while they recover.
Start my Group Insurance review